

How Young Drivers Can Reduce Insurance Costs in Ireland
#AD
Sponsored by KennCo Insurance
Car insurance is often one of your biggest expenses when you start driving. Young drivers in Ireland under the age of 25 are generally considered a higher risk by insurers because of their lack of experience on the road, combined with factors such as the make and model of the car you're trying to insure, its age and even where it's stored.
But there are ways you can help bring the cost down by understanding what insurers are looking for when they are calculating your premium.
How do insurers calculate risk?
Insurers assess a range of information to work out the likelihood and potential cost of a claim.
For a young driver, factors can include your age, driving experience, type of driver's licence, claims history, the type and value of the car, engine size, where the vehicle is kept, how it is used and the estimated annual mileage.
Young drivers under 25 tend to have higher premiums because of less driving experience and they are more likely to be involved in an accident than older, more experienced drivers, according to data from the Road Safety Authority (Driver spotlight report: Fatalities and Serious Injuries 2020-2024).
What can lower car insurance premiums over time?
The best approach is to focus on building a clean driving history. Each year you drive without making a claim can help you grow your no claims bonus, which may result in a lower premium when it comes to renewing your policy.
Passing the driving test can also help because a fully licensed driver has more experience than a learner, and premiums can become cheaper as that experience builds.
Experience gained as a named driver can also be valuable, depending on the insurer.
Mileage limits
Mileage is another factor worth considering because the more time you spend on the road, the more opportunities there are for something to go wrong. The amount of driving you do per year can affect the price of a policy because the risk of a claim increases with the amount and frequency of driving.
If you genuinely only drive a few thousand kilometres a year, make sure your quoted mileage reflects that.
Estimate your mileage accurately and don’t make up a low figure to secure a cheaper premium. The information you provide when getting a quote needs to reflect how you actually use the car, and you should contact your insurer if your circumstances or usage change.
Named drivers
Adding an experienced driver like a parent or older sibling to your policy as a young driver can sometimes reduce the premium, depending on the insurer and the circumstances.
A parent with many years driving experience may make the overall risk profile more favourable, and being a named driver on another policy can also help young motorists build recognised driving experience.
It's important to avoid 'fronting', which is where you as the main driver of the car fraudulently declare someone else as the main driver, usually a parent, to reduce the cost of the insurance premium. Fronting is illegal and can result in the cancellation of your car insurance policy, a fraud conviction or both.
Telematics or 'black box' insurance
You may have heard of telematics or 'black box' insurance, which involves installing a telematics device to your car to monitor your driving behaviour, like mileage, speed, length of journeys and the time of day the car is used.
For a young driver, telematics can potentially give an insurer more information about your real driving behaviour rather than relying entirely on statistics about your age and experience. In turn you can get better rates on car insurance.
The important thing is to understand exactly what a particular policy monitors and what rules apply before signing up. A policy that rewards responsible driving can be useful, but if you regularly exceed the agreed mileage or drive in ways that breach the policy conditions, you may not get the expected benefit.
Choosing the right first car
The car you want to insure also influences the premium you will pay. You might be tempted by a powerful hot hatch as a first car, but insurance is likely to be much more affordable on a smaller, lower-powered one. Insurers rate cars according to risk and lower-powered cars tend to attract cheaper insurance premiums.
For that reason it's worth getting insurance quotes before buying the car. Two similarly priced cars can have very different insurance costs. Choosing the car first and discovering the premium afterwards can be an expensive mistake.
Keeping the car secure can also help, while remember modifications can increase your insurance and should always be declared to your insurer.
Check out this article for the Best First Cars for Young Drivers.
Type of car insurance
Consider the type of policy cover you need. If you have an older car with a lower market value, third party fire and theft may be worth considering, depending on your circumstances and the level of cover you want. Fully comprehensive car insurance may be more suitable if you've spent a lot of money on a newer, high-value car.
Pay your premium annually
You may have the option to pay your car insurance monthly, but this can cost more overall than paying the annual premium in one go. Check the total amount payable under each option before deciding how to pay.
Increase your voluntary excess
The voluntary excess is the amount of money you agree to pay in the event of a claim. Increasing this amount can lower your premium but just be sure it's an amount you're confident you can pay in the event of a claim.
In conclusion
Providing accurate information, choosing a sensible first car, building up your no claims bonus, gaining named driver experience where possible and driving safely, can all help you work towards more affordable car insurance over time.
Safe and responsible driving is not only important for reducing the risk of an accident but can also help you build a strong driving record and potentially lower your insurance costs in the future.
Young Drivers Car Insurance
For more information or to get a quote, visit KennCo Insurance or call 01 409 2600.
KennCo Underwriting Ltd T/A KennCo Insurance is regulated by The Central Bank of Ireland.

Best First Cars For Young Drivers Ireland (2026)
Best First Cars for Young Drivers in Ireland
Sponsored by KennCo Insurance
Buying your first car is a major milestone - it means finally having the freedom to get to college, work or see friends without relying on lifts.
But what sort of car should you be looking to buy and what will be the cheapest one to insure? These are the most common questions from young drivers embarking on this next step.
In this article we’ve picked out some of the best first cars for young drivers in Ireland, as well as a few tips for getting a car insurance quote.
Top 3 Priorities When Choosing Your First Car
For most young drivers, your first car won’t be your dream car. But it’s your first taste of having your own car, building your driving experience and no-claims bonus, which gradually lowers your car insurance premium over time. Therefore it pays in the long run to be sensible with your purchase, while always striving to drive safely, responsibly and within the law.
1. Easy to drive
Let’s be honest there’s enough to think about as a young driver, between checking your mirrors, hill starts, indicators and gear changes. For that reason, your best bet is a small car that’s easy to get around in, whether that’s city streets or rural roads. Not to mention, simple to park.
Should I go for a Manual or Automatic as my first car?
Whether you go for a manual or automatic car depends on your preference. Automatics are becoming more common, with the rise in hybrid and electric cars. But manual cars still dominate the market for small, affordable used cars. Automatics can be easier to drive in traffic but sometimes carry slightly higher insurance costs because they are often more expensive to repair and replace.
Also, be aware that if you pass your driving test in an automatic car, you won’t legally be able to drive a manual car. Whereas you are covered for both if you pass your test in a manual car.
2. Cheap to run
You may be a student, in your first job or internship, paying rent or saving for a home, so keeping costs down is a must. Don’t just think about the initial purchase price or loan repayments. There’s also the fuel required to run the car, maintenance, tyres and the NCT.
3. Cheap to insure
Young drivers pay more for insurance as cover is provided based on risk of the driver. Statistically young drivers are more likely to be involved in an accident and make a high value claim compared to drivers over the age of 25 years old.
If you want to understand more about why young drivers pay more and how to reduce your premium, even as a young driver, look at our article Car Insurance for Young Drivers in Ireland: Practical 2026 Guide.
Insurance companies assess risk based on a wide range of factors, but the car itself plays a huge role.
How Insurance Groups Work
Vehicles are often categorised into insurance groups, which help insurers estimate how likely a car is to be involved in a claim and how expensive it would be to repair or replace.
Generally, insurers look at:
- Engine size and power output
- Vehicle value
- Repair costs and parts availability
- Safety ratings
- Theft statistics
- Previous claims data for that model
For a cheaper insurance quote, look for cars with smaller engines like a 1.0- or 1.2-litre, as they come with lower risk for young drivers and tend to be more fuel-efficient anyway. Avoid cars with modifications as that will hike up your premium too.
Young drivers are typically looking for a first car on a budget. But bear in mind that cars of ten years or older can be more difficult to insure.
Best First Cars for Young Drivers
Car insurance quotes may vary between insurers so it’s good to shop around, but here we’ve listed first cars that are commonly regarded as some of the more insurance-friendly options for young drivers in Ireland:
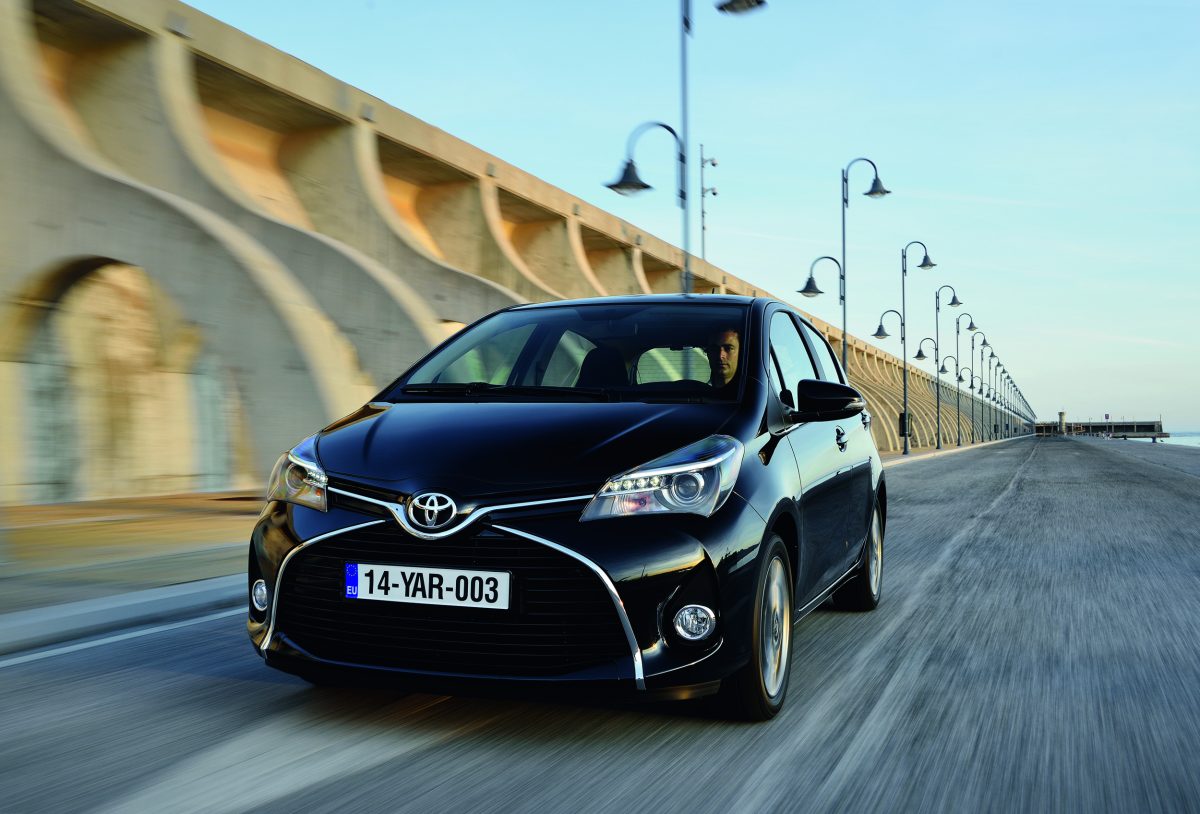
Toyota Yaris
The Yaris has been a staple of Irish roads for over 25 years so you will find lots of used versions online. It’s known for its reliability as well as being fuel-efficient and easy to drive.
Volkswagen Polo
Another one of Ireland’s favourite small cars known for its practicality and solid build quality. The lower-powered versions like the 1.0-litre petrol are not fast but most attractive to insurers.
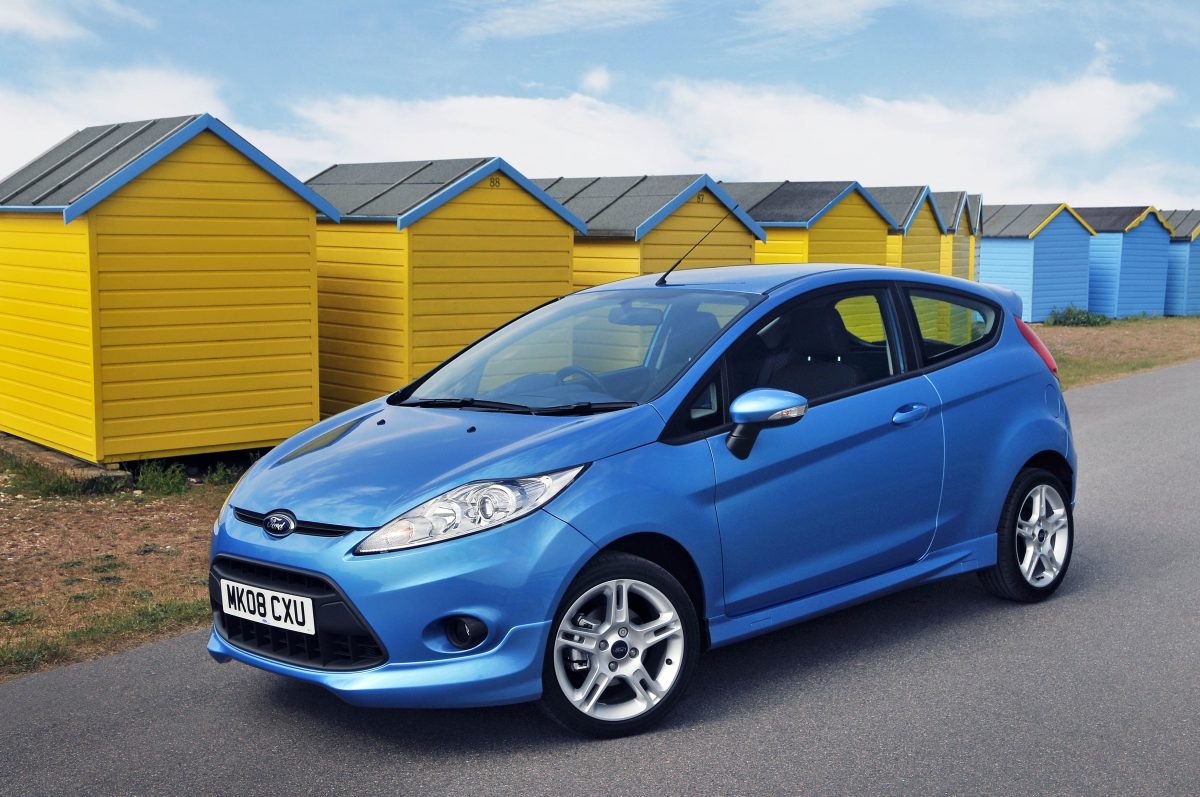
Ford Fiesta
The Fiesta is still one of the most desirable first cars out there with plenty of used ones available. It’s stylish and genuinely fun to drive. Opt for a small engined one and avoid the sportier variants like the ST and Zetec S.
Kia Picanto
Another popular starter car, the Kia Picanto is not fast but it’s small, easy to drive and cheap to run.
Hyundai i10
The Hyundai i10 has been one of the best city cars you can buy for a long time. It’s practical for a small car, and ideal for city streets and parking in tight spaces.
Opel Corsa
The Opel Corsa is a solid choice of first car with plenty of them available. It’s practical and easy to get around in, while small-engined versions will be cheaper to insure.
Suzuki Swift
Known for its reliability, the Swift is a great option for your first car. It's basic inside but it's got a great image and is fun to drive and very efficient.

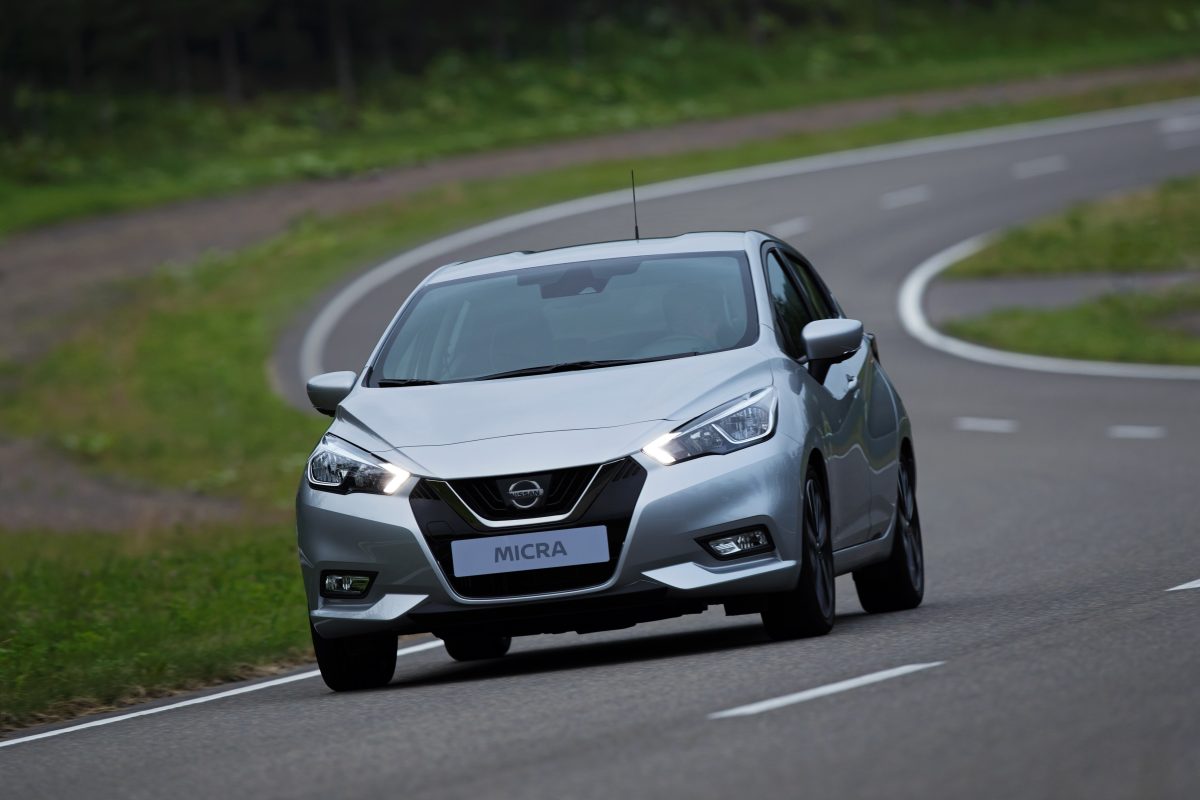
Nissan Micra
The Micra has become a lot more stylish over the years but it’s always been known for its dependability, with plenty of older versions still on Irish roads. That’s always a good sign for its longevity and popularity among young drivers.
Skoda Fabia
The Fabia offers good value to first-time car buyers seeking a practical, efficient small car. Well-proven engines from the Volkswagen Group and sturdy build quality make it a reliable choice.
Premium Pick: Audi A1
The Audi A1 has become a popular choice among young Irish drivers who want something more stylish and premium on a budget. Smaller-engine versions like the 1.0 TFSI can still be relatively manageable to insure compared to larger Audi models. However, insurers may charge more than they would for a Toyota Yaris or Hyundai i10 because repair costs and parts tend to be more expensive.
What about Japanese Imports?
Imported models from Japan like the Honda Fit, Nissan Note, Audi A1 and Volkswagen Golf have become more popular in Ireland thanks to their reliability, automatic gearboxes and high specification. However, it’s worth noting insurers can charge more for imported vehicles because repair costs, parts availability and claims data can differ from Irish-market cars.
Top tip: Always shop around and compare car insurance quotes on the specific model you have in mind before buying to avoid any nasty surprises.

Final word on buying your first car
Remember, your car choice does influence how much you pay for car insurance along with other factors.
For first-time drivers, choosing a sensible car can make a major difference not just for insurance costs, but also for fuel economy, maintenance and passing the NCT.
Your dream car is something you can work towards. For now, building your driving experience, no-claims bonus and keeping running costs down is the smartest approach for young drivers.
Young Drivers Car Insurance
For more information or to get a quote, visit KennCo Insurance or call 01 409 2600.
KennCo Underwriting Ltd T/A KennCo Insurance is regulated by The Central Bank of Ireland.

Car Insurance for Young Drivers in Ireland: Practical 2026 Guide

SPONSORED BY KENNCO INSURANCE
The cost of car insurance for young drivers in Ireland can be a bigger obstacle to getting started as a new driver than the driving test itself.
But understanding why premiums are higher for young drivers and what you can do about it makes a big difference as you go about getting your first car insurance policy.
In this article, we've teamed up with our insurance partner KennCo Insurance to help get you started with insights and practical tips for new drivers.
Types of Car Insurance Cover Explained
There are three types of car insurance cover available for young drivers:
1. Third Party
Third Party insurance gives you the most basic level of cover and is the minimum legal requirement in Ireland. It insures you against a claim made against you, such as property damage or personal injury, but will not cover the damage to your car.
2. Third Party Fire & Theft
Third Party Fire & Theft gives you the same cover as third party insurance, but includes additional cover for fire or theft of your car.
3. Comprehensive
Comprehensive car insurance includes third party fire and theft cover, but also covers any accidental damage to your vehicle. For example if your car is damaged while parked by an unknown person or damage to your vehicle in an accident that is your fault or where the fault can't be proven. This cover is more expensive than third party but is recommended for young drivers.
What age must you be to get car insurance in Ireland?
For insurance purposes, young drivers are those aged between 17 and 24 years old. You must be at least 17 years of age to get car insurance in Ireland, which is the same as the minimum age required to get a driver's permit to learn how to drive a car.
However, the age at which you can get cover does depend on the insurer.
Noel Gavin, Marketing Manager at KennCo Insurance, says, "For many families, getting a 17 or 18 year-old insured, whether that’s a car of their own or the family car, can be quite tough."
The company has lowered the minimum age to hold a private car insurance policy in your own name from age 19 to 17 years of age, as of January 2026.
This means young drivers can access competitive car insurance earlier in their driving careers. Parents insured with KennCo can also now add children aged 17 and older to their policy as a named driver.
To get your first car insurance policy, you will need to provide a valid learner driver's permit or driving licence.
Why Young Drivers Pay More for Car Insurance
Age is a big factor as to why young drivers struggle to get cheap car insurance. It is typically more expensive to get car insurance until you are 25 years old because car insurance is based on the risk of the driver.
Younger and less experienced drivers typically tend to pay higher premiums because statistically at this age you are more likely to be involved in an accident and make a high value claim compared to drivers over the age of 25 years old. Insurance companies have data to back this up. Data from the Road Safety Authority (RSA) also consistently shows that road users aged 16-24 are the highest-risk group on Irish roads (Driver spotlight report: Fatalities and Serious Injuries 2020-2024).
If you are a young driver taking out your first insurance policy, you won't have the benefit of a No-Claims Bonus either.
What is a No-Claims Bonus?
A no-claims bonus is a discount a driver receives on their insurance premium based on the number of years they have held a car insurance policy without making a single claim.
The discount becomes higher the more years you’ve held your policy without an accident. A no-claims bonus only applies to the driver who has taken out the policy in their name.
A no-claims bonus will be worth a different amount to each insurer, but you will likely get a considerable discount if you have not made a claim in over five years or more.
To earn a no-claims bonus, you must not have made a claim for an entire year on your policy, and this will reward you with a one-year no-claims bonus. The more years of claims free driving you build up, the more your insurance premium will decrease each year.

Practical tips for young drivers to get cheaper car insurance
There are several ways you can reduce your car insurance as a young driver:
1. Pass your driving test as soon as possible
The sooner you pass your test as a young driver, the better. Your insurance premium will go down the longer you hold a full driver's licence.
2. Be sensible about your car choice
High-performance vehicles, SUVs or cars with large engines typically come with higher premiums. For a cheaper insurance quote, opt for a car with a smaller engine, as they come with lower risk for young drivers. Not only can this save you money on insurance, it’s also likely to be more fuel-efficient. Avoid any modifications as you will end up paying more for them because these sorts of vehicles are more likely to be involved in claims.
3. Use any named driver experience
If you've been a named driver on a policy, your insurer will take that experience into account. If you have not made a claim, you will be rewarded for that.
4. Add a named driver
Adding a more experienced driver to your policy like a parent or grandparent can also lower your premium, as your insurer may feel that you will be safer under their guidance. This is provided that the named driver hasn't made a claim or has penalty points.
5. Keep your car safe
Adding better security like an alarm, parking your car off-street or keeping it in a garage may lower your insurance cost as you’re less likely to claim for a theft.
6. Pay annually instead of monthly
Most insurers charge extra for the convenience of spreading payments out over the year due to the added administration and interest fees involved. If you can afford it, try paying for your insurance in one go instead of monthly instalments.
7. Increase Your Excess
Your excess is the first amount of a claim that you must pay. For example, if your excess is €500 and you cause €2,000 worth of damage to your car (assuming the loss is covered), your insurer will pay €1,500 for repairs.
8. Shop around
Make sure to shop around for cheaper young driver insurance and get a quote from multiple insurers.
For a fast and reliable young driver car insurance quote, contact KennCo on 01 409 2600 today, or visit their website for an online quote.
KennCo Underwriting Ltd T/A KennCo Insurance is regulated by The Central Bank of Ireland.

EV Charging: It’s not just about the plug
Sponsored by Electrassure

At first glance, electric vehicle charging seems straightforward - plug in, power up and drive away. But when you step into the world of commercial EV charging, it quickly becomes clear that it is far more sophisticated than simply supplying electricity. This is an ecosystem built on infrastructure, technology, user experience, and sustainability - all working in harmony.
For businesses entering this fast-growing market, a few charge points and a power line aren’t enough. Success depends on strategy, reliability and foresight. Companies like Electrassure understand that thriving in this industry means combining technical excellence with long-term vision. So, what does it really take to build a charging network that lasts? Let’s explore the layers behind this evolving sector.
Building on Solid Ground: Infrastructure First
Unlike petrol forecourts, EV charging networks are not plug-and-play installations. They demand careful planning from the outset, including consideration for grid access, user flow and scalability. The location of each charging point remains one of the most important factors. The best sites are not just visible but logical - places like shopping centres, commuter routes or business parks, where drivers are already spending time. Accessibility, lighting and safety all contribute to the overall appeal. In the end, it is not just about providing power, but delivering genuine convenience.
A prime location is only half the equation. A reliable and consistent power supply is equally vital. Charging hubs require high-capacity, stable connections that can handle fluctuations in demand. Partnering with local utilities, installing backup energy storage and planning for future expansion ensures stability and reliability when usage peaks.
Putting the Customer First
As competition increases, the customer experience becomes one of the most significant differentiators. Drivers expect ease, speed and reliability, and any friction in the process can deter them from returning.
No one should need instructions to use an app or a kiosk. A seamless interface, flexible payment options and quick transactions are essential. Whether through contactless payment, a mobile app or an account-based system, the process should be as fast and intuitive as filling up a car with petrol.
Speed is another crucial element. Fast and ultra-fast chargers make a tangible difference, especially in high-traffic areas where time is of the essence. The quicker someone can recharge and continue their journey, the stronger the impression your network will leave.
Waiting time can also become an opportunity. Providing Wi-Fi, comfortable seating, shaded areas or nearby amenities transforms charging from a chore into a positive experience. When handled thoughtfully, those 15 to 30 minutes can strengthen customer satisfaction and loyalty.
Smarter Charging Through Technology
The real innovation in EV charging lies in the technology working quietly behind the scenes. Smart systems are transforming how energy is distributed, stored and consumed. Adaptive power management systems monitor grid conditions in real time, adjusting the charging output automatically to maintain efficiency. This approach keeps infrastructure stable, controls costs, and can even reward customers for charging during off-peak hours.
Every charging session generates valuable data - from usage patterns and dwell times, to payment behaviour. When analysed effectively, this information helps operators predict demand, minimise downtime and make smarter investment decisions about where and when to expand their network. Transparency also plays a role in building trust. Giving users access to real-time information about charger availability, estimated wait times, or nearby facilities helps reduce frustration and elevates the brand experience.

Sustainability: Beyond the Buzzword
Electric vehicles already represent a cleaner alternative to petrol transport, but charging networks have the power to go further. The most forward-thinking operators build sustainability into every stage of their operations. On-site renewable energy sources such as solar panels or wind turbines can significantly reduce reliance on the grid while lowering operational costs. This visible commitment to sustainability also appeals to environmentally conscious drivers.
Energy storage adds another layer of intelligence to the system. By storing energy when it is abundant or inexpensive and deploying it during peak times, operators can reduce strain on the grid and maintain consistent service levels. Even with these measures, some emissions are inevitable, from construction to maintenance. Carbon offset programmes provide an effective way to balance these unavoidable impacts and reinforce an organisation’s environmental credentials, which are increasingly important in a market shaped by ESG values.
Navigating Regulation and Compliance
In such a fast-moving industry, regulations are constantly evolving. Staying compliant is not just about avoiding fines - it is about remaining competitive. Local knowledge is essential. From safety standards and accessibility requirements, to data protection laws, the details differ across regions. Taking advantage of government incentives, grants or green energy schemes can also help lower initial costs and accelerate return on investment.
Interoperability is another emerging priority. Drivers do not want to be locked into one provider. Charging stations that support cross-network compatibility through roaming agreements or shared payment systems offer greater convenience and enhance user confidence. This flexibility can be a key factor in building long-term customer loyalty.
The Economics of Charging
Developing and maintaining charging infrastructure requires a substantial upfront investment. Profitability must be considered from the start. Hardware, installation, electricity, maintenance and customer service all contribute to operational costs. Pricing strategies should reflect these realities, while remaining fair and transparent to users.
Revenue opportunities extend beyond charging fees. Subscription models, partnerships with retail sites, or integrated parking packages can add extra value and resilience to the business model. The more ways an operator can enhance customer experience while diversifying income, the more stable their long-term growth becomes.
Managing the Challenges
Even as demand continues to rise, commercial EV charging still faces several operational challenges. Grid pressure is one of the most pressing. As more drivers switch to electric vehicles, the strain on the energy network increases. Collaboration with utility providers and investment in intelligent distribution systems can help maintain stability during high-demand periods.
Cybersecurity is another critical issue. With financial transactions and user data flowing through every connected charger, protecting those systems is essential. Regular software updates, security audits and encrypted communications safeguard not only the network, but also the brand’s reputation.
What’s Next for EV Charging?
The pace of change within the EV charging landscape is remarkable, with new technologies pushing the boundaries of what is possible. Wireless charging, for instance, is moving from prototype to reality. Vehicles could soon charge simply by parking over a pad, offering unmatched convenience.
Vehicle-to-grid (V2G) technology is another exciting development. It enables EVs to send stored energy back into the grid during peak times, helping to balance demand and even allowing drivers to earn credits or income. Networks that adopt V2G early will play a central role in creating a more flexible and responsive energy system.
Ultra-rapid charging represents the next major leap forward. New systems promise to deliver hundreds of kilometres of range in under 15 minutes. When this becomes standard, the difference between refuelling a petrol car and charging an EV will all but disappear.
Conclusion: Powering a Smarter Future
Commercial EV charging is about far more than electricity. It is about creating intelligent, reliable and sustainable infrastructure that meets the needs of modern drivers. Success in this space depends on thinking beyond the plug - combining seamless user experience, innovative technology, and a firm commitment to environmental responsibility.
Businesses that embrace this broader perspective will not only stay ahead of the curve but also shape the future of sustainable transport.


No Claims Bonus Protection: Is It Worth It?

Do you need no claims bonus protection with your car insurance in Ireland?
SPONSORED BY KENNCO INSURANCE
At Changing Lanes, we have teamed up with the experts at KennCo Insurance to explain what is no claims bonus protection and is it worth it.
A no-claims bonus is a discount a driver receives on their insurance premium based on the number of years they have held a car insurance policy without making a single claim.
The discount becomes higher the more years you've held your policy without an accident. A no-claims bonus only applies to the driver who has taken out the policy in their name.
No Claims Bonus
A no-claims bonus will be worth a different amount to each insurer, but you will likely get a considerable discount if you have not made a claim in over five years or more.
To earn a no-claims bonus, you must not have made a claim for an entire year on your policy, and this will reward you with a one-year no-claims bonus. The more years of claims free driving you build up, the more your insurance premium will decrease each year.
This is why drivers should consider protecting your no-claims bonus.
There are two options available to drivers to allow you to keep your no-claims bonus - Full No Claims Bonus Protection and Step Back No Claims Bonus Protection.
1. Full No Claims Bonus Protection
When you take out your insurance policy, you will have the option to protect your no claims bonus. For an additional fee on your policy, your bonus will be protected even if you make a claim.
Purchasing a Full No Claims Bonus Protection is the most expensive option but does offer the most significant protection. So despite making a claim on your insurance cover, your no-claims bonus is still active.
Some insurers may apply limitations to this, so make sure you know your insurer's terms and conditions. These may include restricting the amount of time you can make a claim before your no-claims bonus is affected. Even with no claims bonus protection in place, some insurers may still factor your accident into account.
2. Step Back No Claims Bonus Protection
Step Back No Claims Bonus Protection is when the policy holder protects part of their no-claims bonus. It typically costs less than full protection but offers you less cover too. This protection may apply when you're at fault for an accident. Instead of losing all of your five-year no-claims bonus, you only lose two years and effectively 'step back' to having a three-year no-claims bonus.
Benefits of No Claims Bonus Protection
There are several benefits to having no claims bonus protection, whether it's a full no claims bonus protection or step back no claims bonus protection.
The following are good reasons why you should consider protecting your no claims bonus next time your car insurance policy is up for renewal:
- Cost: Having a no claims discount will significantly decrease the cost of your car insurance. Without protection, you could lose it all in just one accident.
- Security: By protecting your no claims bonus, you will be keeping your discount secure. You will continue to pay less on your premium even if you are involved in an accident. You could receive a reduction of up to 67% by having a full no claims bonus.
If you're thinking of purchasing a new car insurance policy, follow this link to contact KennCo Insurance for a secure CAR INSURANCE QUOTE.
Now find out more about how younger drivers can get cheaper car insurance.

How Young Drivers Can Get Cheaper Car Insurance

Are you a young driver in Ireland looking for cheap car insurance?
SPONSORED BY KENNCO INSURANCE
At Changing Lanes, we have teamed up with the experts at KennCo Insurance to help you with insider tips on how to get the best deal on your car insurance!
If you are a young or new driver, it may be tricky to find affordable and cheap car insurance. As a new driver, you have overcome the hard part by passing your test and getting on the road. But at the end of that, you may feel that getting a suitable car insurance cover is difficult. There are some ways to reduce your insurance premium if you are under 25, which we will explain in this article.
Am I considered a young driver?
You are considered a young driver if you are aged between 18 and 24. It is typically more expensive to get car insurance until you are aged 25. At KennCo, we insure young drivers of 19 years old and above. If you are 18 years old, you may obtain car insurance as a named driver on a policy with an experienced driver, such as one of your parents.
Why is car insurance more expensive for younger drivers?
There are many reasons why insurance is pricier for young drivers. Car insurance premiums are calculated based on the risk of the driver having an accident. Statistically, young drivers are more likely to be involved in an accident than drivers over 25. Drivers over the age of 25 will be more experienced drivers, so the risk of an accident decreases. Young drivers car insurance should decrease with every year of your No Claims Bonus.
Types of car insurance cover for young drivers
There are two types of car insurance cover available for young drivers. it is a legal requirement to obtain car insurance for driving.
1. Comprehensive Car Insurance
Comprehensive cover means that your insurer will cover the cost of repairing your car and, if necessary, the cost of any damage or injury to a third party if you are involved in an accident.
2. Third-Party Fire & Theft Car Insurance
Third-Party Fire & Theft covers you if your car is damaged by fire or from theft. This cover also extends to any damage or injury to third parties where you are at fault for the accident. This type of insurance does not cover damage to your car.
Tips for reducing the cost of Young Drivers Car Insurance
There are several ways to reduce your car insurance as a young driver:
- Named driver experience: Your insurer will take any named driver experience into account when you take out an insurance policy in your own name. They will reward you for your excellent driving history if you have not made a claim.
- Pass your test! If you are a learner driver, then the sooner you pass the test, the better. Your insurance will decrease the longer you hold a full license.
- Your choice of car: Choosing a car with a lower-powered engine will reduce the price of your insurance as they are less likely to be involved in an accident. You should also avoid any cars with modifications as you will end up paying extra for them.
- Security: If you add more security measures to your car, your car will be safer from theft and may lower your insurance cost as you’re less likely to claim theft.
- Add a driver: Another way to lower your premium is to add a driver with more experience to your policy. If a parent to partner has been driving for many years, your insurer may feel that you will be safer under their guidance.
At KennCo Insurance, we understand that it can be challenging for young drivers to get their first car on the road. That’s why we’re offering affordable and reliable car insurance for young drivers. Follow this link to the Kennco website to get a Car Insurance quote in minutes.
Now read our article on No Claims Bonus Protection with your next car insurance policy. Is it worth it?

How To Buy The Best Bike Rack For Your Car

SPONSORED BY MICKSGARAGE.COM

Are you looking for a new activity this summer that is fun, healthy, and free? Cycling is a great way of getting family and friends together and adding more fun, freedom, and adventure back into life once again.
With a simple bike rack, you can safely bring your bikes around Ireland on your staycation this summer. Or stay local and explore your favourite places and greenways on two wheels!
But what’s the best bike rack for my car? Cheap or premium? Towbar or roof-mounted? There are lots of different types of bike carriers available for your car, so we have teamed up with the experts at MicksGarage.com to guide you through your options, provide some top recommendations, along with essential information you need to know when choosing the best bike rack.
Micksgarage.com is an Irish company with an excellent website stocking an extensive range of bike racks and other adventure, travel, and road trip accessories for summer 2021.
Read our article to discover the best bike racks in Ireland and start planning your next adventure now!

What do I need to think about when choosing a bike rack for my car?
- The number of bikes you want to carry at the same time. Just one bike or two, three or four?
- Position you want to carry the bikes: a) On the rear door (boot door), b) On the roof of the car, c) On the towbar of the car.
- What type of bikes you want to carry? The only suitable carriers for electric bikes will be platform towbar carriers due to the weight of the bike. If it’s a bike with a very wide tyre width, you’ll need to check that the bike carrier (platform towbar bike racks) will provide enough space to get the tyre in.
Types of bike rack
There are three types of bike carriers for cars you can choose: rear door mounted rack, roof mounted rack or tow bar mounted rack.
1. Rear Door Mounted Rack
Benefits
- Convenient and affordable
- They fit most cars on the road
- Small, quick to set up and remove - only a little lifting of bikes is required.
- Easy to store
Things to consider
- Check your vehicle is compatible with a rear door bike rack. If your car has a plastic spoiler, generally it’s not advisable to carry a bike rack on the rear of the car as the weight of the rack and bikes can cause pressure on the spoiler and because it’s only plastic, could damage it.
- Ladies’ bikes will need a cross bar adapter so that they can easily and safely fit on a rack where the frame of the bike needs to sit on the rack (also available on MicksGarage.com).
Best Buy: UNIVERSAL 3 BIKE CARRIER

The Universal 3 rear door mounted bike carrier comes highly recommended from the MicksGarage team. It can securely hold three bikes and supports a maximum weight of 45kg. The carrier has a universal design and can be adjusted to fit most types of cars including hatchbacks, saloons, and estates. It can also fit 4x4s as well. It’s easy to assemble and folds away for easy storage!
Buy the Universal 3 here.
Browse more rear door mounted bike racks.
2. Roof Mounted Bike Rack
Benefits
- Safe and convenient to use.
- Very secure with locking function available.
- Keeps the boot completely free for access.
- No bikes in your field of vision while driving.
Things to consider
- You need roof bars (also available on MicksGarage.com) and a roof mounted bike rack to carry a bike on your car in this way.
- Lifting of bikes is required to get them on the roof.
- Consider if you’re going to be carrying a roof box or a canoe on the roof at the same time as well.
Best Buy: AGURI ACUDA (Black or silver)

The Aguri Acuda II Bike Rack Carrier is a beautifully designed product. The Micksgarage team say that this carrier is as high quality as a Thule Bike Rack but for a lot less and comes highly recommended. It’s available in black or silver. The carrier mounts to roof bars by a T-Track system (which is included). The carrier can hold wheels sizes ranging from 16" to 29" in diameter and tyre walls with a maximum of 80mm. Wheelbases ranging from 75cm to 130cms fit perfectly. If you love your bike, you'll love the Aguri Acuda!
Buy the Aguri Acuda here.
Browse more roof mounted bike racks.
3. Tow Bar Rack
Benefits
- Extremely safe, arguably the safest way of carrying bikes.
- Very fast to install and remove.
- They look great.
- Very secure with locking function available.
- Can carry the heaviest weights so ideal when carrying a number of bikes or an electric bike.
Things to consider
- You will need to have a towbar installed on your car for this (also available from MicksGarage).
- If you have an electric bike, you really should be only carrying it on a towbar mounted carrier due to the weight of them.
Best Buy: PERUZZO PURE INSTINCT RANGE

For more than 25 years, Peruzzo has been producing bike carriers for cars made with high quality materials. The Peruzzo Pure Instinct range of carriers is a best buy if you are looking for a secure towbar mounted bike rack. Models available from the MicksGarage website can carry up to four bikes. Quick and easy to fit and remove, with a very compact and functional quick release system. Tilts for easy boot loading using a simple foot pedal. Supplied with grab arms for all bikes. Doubly safe with extra safety strap fixed to frame and complete with homologated rear light bar.
Buy the Peruzzo Pure Instinct Range here.
Browse more tow bar mounted bike racks.
Top Tip!
On the MicksGarage.com website, there is a handy tool to help find the best fit for your car for roof bars, tow bars or any other technical part of your vehicle. Simply enter your car registration number and you will be given the best matches for the exact model of your car! For browsing bike racks, you can browse by type of rack to help choose the right one for your car.
If you have any questions or need technical assistance you can call the team at 01-5311337 to speak to a Bike Rack Expert.

How much do I need to pay for a good bike rack?
Bike racks vary in price from €50 to €600. It all depends on the type of rack you want (rear door, roof, or towbar), how many bikes you want to carry at the same time, and your personal preference for what style will suit your car the best.
What essential features should any bike rack have?
This will vary depending on the type of rack:
1. Carrying Weight
Check the maximum load before you buy. Platform towbar mounted bike carriers can carry the heaviest weights, important for electric bikes as they are much heavier than standard bikes.
2. Security
Roof mounted and tow bar mounted bike racks are more secure because they come with locks and keys to secure your bikes to the rack.
3. Bike Tyre Width
This is only important if you have a very wide tyre on your bike. If so check that the platform towbar bike rack provides enough width for your tyre to slot into.
Are bike racks easy to fit?
Yes. There’s a little bit of assembly involved with some models, but it is not complicated, and full instructions are provided. In terms of fitting them to your car, it is very straightforward, and full guided instructions are included with each rack.
Do I need any other safety accessories?
Buying additional foam padding can protect your car and your bike from scratches when you mount/dismount your bike and rack. You can also buy bungee chords or ratchet tie down straps. These are useful if you want to hold things in a little tighter for extra security. There are even wall mounted bike racks available so you can store your bike neatly in your shed or garage when it’s not being used! Browse bike racks accessories here.
By Caroline Kidd
MicksGarage.com have the widest range of bike racks on their website. Check out the full range of bike racks from MicksGarage here.
They are known for fast delivery and excellent customer care, with almost a million happy customers to date and are rated ‘Excellent’ on Trustpilot! Check out the MicksGarage.com website for a huge range of staycation and road trip accessories to make your next adventure awesome – paddle boards, roof boxes, roof bars, gadgets, tents, BBQ’s… and loads more …


Inver Xtra Now Available Nationwide

Inver, Ireland's fastest growing forecourt network, has launched Inver Xtra, a new and improved standard petrol and diesel with the benefit of an additive. It's available now nationwide from your local Inver fuel retailer.
Chris O’Callaghan, Inver’s Managing Director, says: “Inver Xtra will now be our standard fuel. Our high quality petrol and diesel fuels will now have the benefit of an additive. For the past 35 years Inver has been a reliable supplier of unparalleled quality fuels to the Irish market. We are delighted to continue to deliver on our quality assured fuel promise with Inver Xtra."
Here's everything you need to know about Inver in Ireland and their new additized fuel product.
Who are Inver?
Inver has been supplying fuel in Ireland since 1984. Their retail network was established in 2012 and they now have 60 retail outlets in Ireland and growing. The name of the company comes from the Gaelic word for estuary and is inspired by the company's roots at Foynes, County Limerick, on the Shannon Estuary.
Why are Inver making the news?
Inver has just launched Inver Xtra, a new, even better additized fuel that will be the standard fuel now available across Inver retailers in Ireland.

What are fuel additives?
Fuel additives are compounds formulated to enhance the quality and efficiency of petrol and diesel used in motor vehicles.
What's so special about Inver Xtra?
According to Inver, their Xtra fuels have multiple benefits for the Irish motorist:
- Improves fuel burning efficiency reducing car emissions
- Reduces corrosion for longer engine life
- Cleans your engine to increase its power and performance
Inver say that your car will benefit from the first tankful of Inver Xtra, but optimum benefits are gained from continuous use of the new petrol and diesel.
Why has Inver launched this new product?
To affirm their commitment to Irish motorists and to continuously provide the very best fuel at competitive prices.
Ben Lenihan, Inver’s Retail Director, says: “As Ireland’s fastest growing service station network, launching Inver Xtra was the next step in our nationwide expansion. In keeping with our quality commitment, we are working with a leading international additives provider. They have a long and outstanding history as a global supplier of fuel performance packages and their highly effective formulations bring out the best in fuels and engines. Inver Xtra will provide our customers and the Irish motorist with an even higher quality fuel."

So where can I find my local retailer to try the new Inver Xtra fuel?
Check out the map here on the Inver website to find your local Inver service station.
Anything else we should know about Inver?
Every tank does some good for your car, your pocket and your community. Every time you fill up at an Inver service station a cent goes into the ‘tank’ to help local community projects supporting children, families and education, as part of their award-winning Leading Lights community programme. Over 143 organisations around their network have been supported so far by Inver's Leading Lights.

Why is Changing Lanes working with Inver?
At Changing Lanes, we support any business who is improving their product for the benefit of Irish consumers, in particular motorists. Ireland has a fleet in excess of 2 million passenger cars, predominantly petrol and diesel cars. In conjunction with other measures - for example the trading of older vehicles for newer, more efficient models with lower emissions - we support Inver for bringing an additized fuel to market that can help the Irish fleet to run better.
Caroline Kidd
Disclosure: This post has been sponsored by Inver Energy.
